1. Operational Cost
25 BPS0.25% of the loan amount
$500,000 × 0.25% = $1,250
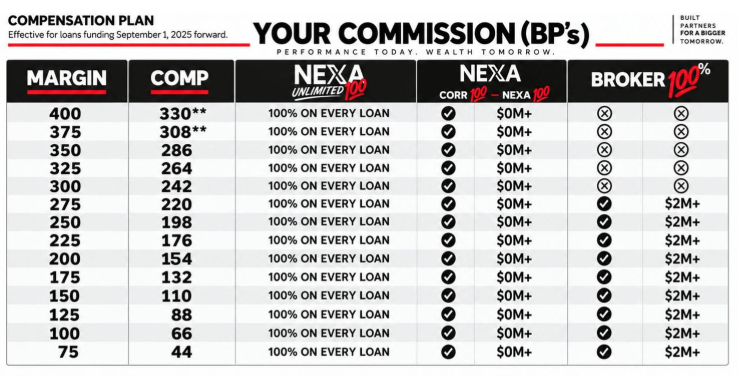
***Maximum compensation to a loan officer will not exceed 300 bps. Any amount above that threshold is allocated to the overage ledger. Revenue share levels unlock based on 1st level recruits. Revenue share is paid from company profit, never from loan officer compensation.
The Standard NEXA Loan Officer Compensation NEXA FEE STRUCTURE applies to Non-Delegated loans up to 400 BPS and Broker Deals up to 275 BPS under $2M per month.
0.25% of the loan amount
$500,000 × 0.25% = $1,250
Of the commission left after the operational cost
($13,750 − $1,250) × 12% = $1,500
Applied to the remaining amount for eligible W-2 compensation scenarios; not applied to the 1099 scenario.
($13,750 − $1,250 − $1,500) × 10% = $1,100
Let's use a $500,000 mortgage loan and a 275 basis point (2.75%) gross commission rate. The gross commission paid to NEXA is $13,750.
| Description | Amount |
|---|---|
| Gross commission (275 BPS) | $13,750 |
| Operational cost (25 BPS) | −$1,250 |
| Revenue share (12%) | −$1,500 |
| 1099 loan officer compensation | $11,000 |
| Additional W-2 deduction (10%) | −$1,100 |
| W-2 loan officer compensation | $9,900 |
Enter your average loan amount and expected monthly closings. Select W-2 or 1099 to see a personalized standard-plan illustration.
| Commission breakdown (per loan) | Amount |
|---|---|
| Gross broker commission (275 BPS) | |
| Operational cost (25 BPS) | |
| Revenue share (12% of post-operational balance) | |
| W-2 deduction (10% of remaining) | |
| Estimated loan officer compensation |
For illustration only, not a guaranteed offer of compensation or a tax projection. The 10% W-2 deduction is modeled as provided and should not be confused with an individual's final federal tax liability or payroll withholding. Actual pay varies with eligibility, jurisdiction, written compensation agreement, loan-level limits, expenses, and applicable law. No NEXA 100 waivers are included in this standard-plan calculator.